Traditional Quantitative
Data and models find opportunities
Systematic screening across large universes, processing market and financial data at a scale no individual analyst could cover.
BreadthQT Quantamental brings financial theory, data science, quantitative models and fundamental investment logic into one systematic research framework.
Built around systematic quantitative research, the QT Quantamental system brings together financial theory, data science, quantitative modelling and fundamental investment logic — analysing data across multiple dimensions to identify high-quality, reasonably priced companies with genuine investment potential.
Traditional Quantitative
Systematic screening across large universes, processing market and financial data at a scale no individual analyst could cover.
BreadthTraditional Fundamental
Deep examination of how a company operates, the quality of its financials and the durability of its long-term value.
DepthThe QT system screens and scores a broad universe of equities through systematic data analysis and quantitative models, building a pool of high-quality candidates. Fundamental investment logic is then applied to review the portfolio and control risk, forming a more complete investment decision framework.
Core process
Five stages take raw market information through to a constructed portfolio — each one systematic, repeatable and reviewable.
See the core logicThe system continuously analyses large volumes of market, corporate and transaction data, translating complex information into investment signals that can be quantified and compared.
Equities are analysed systematically across multiple quantitative dimensions, searching a broad universe for companies with potential investment value.
The QT system integrates distinct investment signals into a composite score, ranking equities to establish a pool of high-quality candidates.
Where the models find opportunity, the investment research team reviews the portfolio through a fundamental and investment-logic lens — testing whether model output holds up against real business and investment reasoning.
Candidate holdings are optimally allocated based on stock scores, risk characteristics and portfolio constraints, producing the final investment portfolio.
Multi-factor screening reads a company from seven angles at once. No single dimension decides anything on its own — a score only means something once all seven are seen together.
Quality × Value × Growth × Behavior
QT is not a search for whatever is rising fastest. It is a search for:
Companies with stronger operational and financial quality.
Equities trading at valuations that make sense.
Companies whose growth is substantiated by data and business logic.
Opportunities where market behaviour has pushed price away from value.
Use data to find mispricing. Use fundamentals to judge real value.
Each approach is strong on its own axis and limited on the other. Quantamental is the attempt to keep both.
Powerful data-processing efficiency — but historical data and the models themselves carry real limitations.
Deep understanding of a business — but hard to cover a large universe and vast market datasets at once.
Models raise research efficiency; fundamental logic validates the signals they produce.
Quantamental seeks the strengths of both. Systematic models raise research efficiency, while fundamental logic validates model signals — so investment decisions rest not only on statistical correlation, but on sounder economic and business reasoning.
A systematic process is only as good as the constraints it accepts. Six principles hold the framework to account.
A source of return should be attributable to an understandable factor, not to statistical correlation alone.
A promising hypothesis is put through rigorous testing before it is allowed into the investment process.
Model output is checked against real business and investment logic, not accepted because the number looks good.
Quantitative models supply the coverage; fundamental review supplies the depth neither could reach alone.
Portfolio construction weighs stock scores against risk characteristics and portfolio constraints together.
Every stage is systematic, repeatable and reviewable — the same inputs lead to the same process.
A research-driven quantitative investment framework
The QT Quantamental investment framework references and builds upon the research methodologies of Rayliant Investment Research across quantitative finance, data science, behavioural finance, factor investing and portfolio construction.
Rayliant emphasises translating financial theory and data science into executable investment insight — rigorously testing effective hypotheses drawn from fundamental research before systematically integrating them into a quantitative investment process.
Its research team spans quantitative research, portfolio management, machine learning, global equities and asset allocation.
The research framework behind QT Quantamental rests on cross-disciplinary research capability. Rayliant's publicly listed team includes:
Rayliant Global Advisors
Founder & Chief Investment Officer
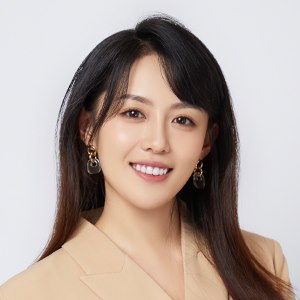
Dr. Jason Hsu is the founder and Chief Investment Officer of Rayliant, and one of the most recognised researchers in quantitative investing and smart beta.
He co-founded Research Affiliates and helped pioneer the RAFI™ Fundamental Index™ approach, publishing extensively across factor investing, smart beta, asset allocation and systematic investment research.
His research has been recognised with awards including the CFA Institute Graham and Dodd Award, the Bernstein Fabozzi/Jacobs Levy Award and the William F. Sharpe Award.
Dr. Hsu has long advocated combining rigorous academic research, data science and real market investment experience — the philosophy that shapes Rayliant's Quantamental research framework.
Selected awards
Chief Research Officer
Chief Operating Officer and Head of ETFs
Head of Fixed Income & Foreign Exchange
Senior Vice President
Alongside a research team of quantitative researchers, portfolio managers and investment professionals.
Rayliant's official research teamThe framework rests on seven disciplines. Each contributes a distinct capability, and together they form the path from research through to risk control.
Turns asset-pricing theory, risk premia and market structure into computable, testable model assumptions — the theoretical floor the whole process stands on.
Cleans, aligns and engineers features from market, corporate and transaction data, turning raw information into comparable, auditable research inputs.
Distils explainable sources of return across quality, growth, valuation and profitability — the building blocks of multi-factor screening and scoring.
Finds non-linear relationships and signal combinations in high-dimensional data, held in check by strict out-of-sample testing to limit overfitting.
Solves the trade-off between stock scores, risk characteristics and portfolio constraints, turning research conclusions into executable allocations.
Explains how systematic biases among market participants push price away from value — the economic account of where mispricing comes from.
Reviews model output against real business logic, testing whether a quantitative signal is backed by durable operations and financials.
Systematic research chain
Straight answers on what this framework is, what it is not, and where its limits lie.
A purely quantitative model processes data at scale but is bounded by history and by the model's own assumptions. Quantamental keeps that breadth and adds a fundamental review step, so a signal has to make business sense as well as statistical sense before it reaches the portfolio.
No. The division of labour is deliberate: the models find opportunity across a universe no individual could cover, and the investment research team reviews the result through a fundamental and investment-logic lens, judging whether the model's conclusion holds up against real business reasoning.
Seven: corporate quality, growth capability, valuation, profitability, market behaviour, investor sentiment and risk profile. Each is set out in the factor section above.
QT's framework references and builds upon Rayliant's publicly documented Quantamental research methodology. Rayliant Investment Research is an independent research organisation; the researchers named on this site are described in their public Rayliant capacity, and nothing here should be read as their endorsement of QT.
No. Models, historical data, backtest results and fundamental research all describe the past and the present; none of them can guarantee future performance. Securities investment carries market volatility and the risk of principal loss.
Not by itself. A backtest is fitted to history and can reward overfitting, which is why out-of-sample testing and a fundamental logic check matter more than an impressive historical curve.
Standing alongside leading model providers to define the standard and the future.
 Qwen
 DeepSeek
 Doubao
 Claude
 ChatGPT
 Kimi
Moving investing from judgement by experience to dual verification by data and logic.
Explore the System